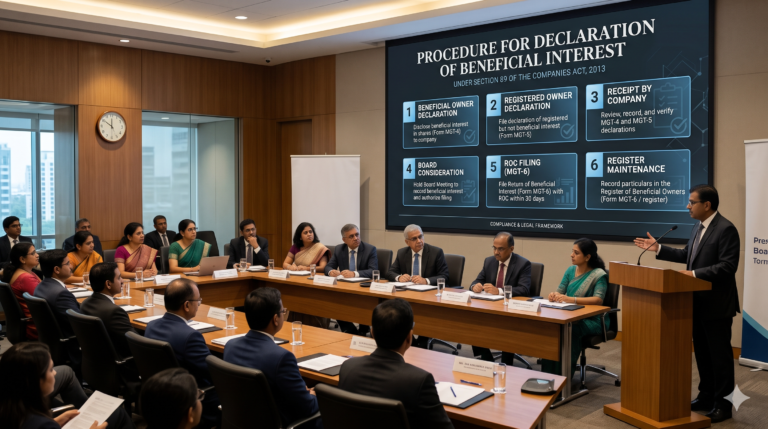
The person whose name appears in a company’s register of members is not always the person who owns the economic interest in the shares. Nominee holdings, such as a director holding one share on behalf of a holding company, are common. Section 89 requires both the registered owner and the beneficial owner to declare such arrangements, and the company to report them to the Registrar.
This article walks through the declarations, the company’s filing obligations, and the designated person requirement introduced in 2023, with the timeline for each step.
Governing law: Sections 88, 89 and 92 of the Companies Act, 2013; Rule 9 of the Companies (Management and Administration) Rules, 2014 Applies to: All Companies, except a Government company that has not defaulted in filing financial statements or annual returns Declarations: Form MGT-4 (registered owner); Form MGT-5 (beneficial owner) Key ROC forms: e-Form MGT-6 (return by company); e-Form GNL-2 (change in designated person) |
Person | Declaration | Timeline |
Registered owner who does not hold the beneficial interest | Form MGT-4, naming the beneficial owner | Within 30 days of his name being entered in the register of members |
Beneficial owner whose shares are registered in another’s name | Form MGT-5, stating the nature of interest and the registered owner | Within 30 days of acquiring the beneficial interest |
Both, on any change in beneficial interest | Fresh MGT-4 and MGT-5 | Within 30 days of the change |
Company | Return in e-Form MGT-6 | Within 30 days of receipt of the declaration |
A common case is a holding company that keeps a nominee shareholder in its subsidiary to meet the minimum number of members. The nominee files MGT-4, the holding company files MGT-5, and the subsidiary files MGT-6 (Section 187(2) read with Section 89).
A note of the declaration is required to be made in the Register of Members (Form MGT-1) against the relevant folio, recording the name and particulars of the beneficial owner.
As good practice, declarations received are placed before the Board, which takes note of them and authorises a director or the Company Secretary to file MGT-6. This is not a pre-condition for filing, which cannot wait beyond 30 days.
The company is required to file a return in e-Form MGT-6 with the Registrar for each declaration received, attaching copies of MGT-4 and MGT-5. A specified IFSC company has 60 days.
The annual return is required to include the details of the designated person.
Effect of declarations. No right in respect of the shares can be enforced by a person who was required to make a declaration but did not (Section 89(8)). Payment of dividend to the registered member discharges the company (Section 89(9)). For listed companies, beneficial ownership is reflected through the significant beneficial owner table in the quarterly shareholding pattern under Regulation 31 of the SEBI (LODR) Regulations.
Default | Provision | Penalty |
Failure by registered or beneficial owner to make a declaration | Section 89(5) | ₹50,000 plus ₹200 per day of continuing failure (maximum ₹5 lakh) |
Failure by company to file MGT-6 | Section 89(7) | ₹1,000 per day on company (maximum ₹5 lakh) and on every officer in default (maximum ₹2 lakh) |
Default in annual return | Section 92(5) | ₹10,000 on company and every officer in default, plus ₹100 per day (maximum ₹2 lakh for company, ₹50,000 for officers) |
Day 0 = Date of receipt of declaration by the company
Timeline | Action | Applies to |
Event + 30 days | MGT-4 and MGT-5 given to the company | Registered and beneficial owners |
Day 0 | Note made in Register of Members | All Companies |
Next Board Meeting | Declarations noted by the Board | All Companies |
Day 0 + 30 days | MGT-6 filed with the Registrar | All Companies |
On change | GNL-2 for change in designated person | All Companies |
AGM + 60 days | Designated person reported in annual return | All Companies |
Disclaimer: The information contained in this Article is intended solely for personal non-commercial use of the user who accepts full responsibility of its use. The information in the article is general in nature and should not be considered to be legal, tax, accounting, consulting or any other professional advice. We make no representation or warranty of any kind, express or implied regarding the accuracy, adequacy, reliability or completeness of any information on our page/article.