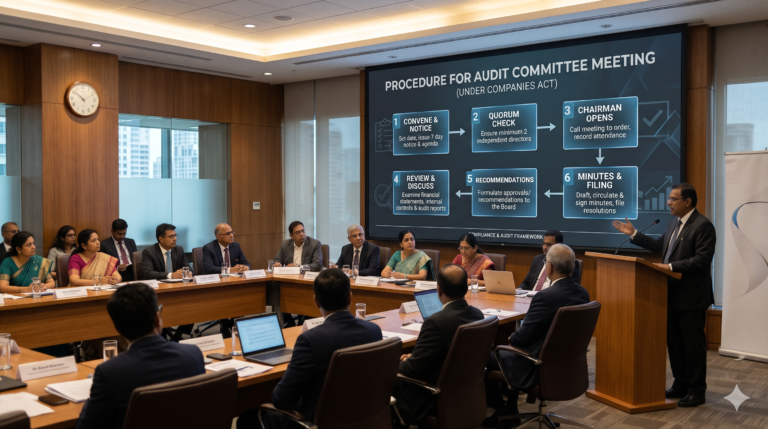
The Audit Committee is the Board’s main oversight body for financial reporting. It reviews the financial statements before the Board approves them, approves related party transactions, oversees the auditors and internal controls, and runs the vigil mechanism. In a listed company, its role is wider still, with a detailed list of functions under the SEBI (LODR) Regulations.
This article sets out which companies need an Audit Committee, how it is required to be composed, and the step-by-step procedure for holding its meetings, with the timeline for each step.
Governing law: Section 177 of the Companies Act, 2013; Rules 6 and 7 of the Companies (Meetings of Board and its Powers) Rules, 2014; Secretarial Standard-1 (SS-1); Regulations 18, 23, 27 and 46 and Part C of Schedule II of the SEBI (LODR) Regulations, 2015 Applies to: Listed Companies and specified unlisted public companies Quorum (Listed Company): Two members or one-third of the members, whichever is greater, with at least two independent directors present Frequency (Listed Company): At least 4 meetings a year, with not more than 120 days between two meetings |
Type of Company | Requirement | Provision |
Listed public company | Mandatory | Section 177 read with Rule 6; Regulation 18 |
Unlisted public company with paid-up capital of ₹10 crore or more, turnover of ₹100 crore or more, or outstanding loans, debentures and deposits exceeding ₹50 crore | Mandatory | Section 177 read with Rule 6 |
Unlisted public company that is a joint venture, wholly owned subsidiary or dormant company | Exempt | Rule 6 (proviso) |
Private company; specified IFSC public company | Not required | – |
Requirement | Companies Act, 2013 | SEBI (LODR) Regulations |
Minimum members | 3 directors | 3 directors |
Independent directors | Majority, including the Chairperson | Two-thirds of members; Chairperson to be independent |
Financial literacy | Majority, including the Chairperson, able to read and understand financial statements | All members financially literate; at least one with accounting or financial management expertise |
Secretary | – | Company Secretary |
Attendance at AGM | – | Chairperson to be present to answer shareholder queries |
(Applicable to Companies required to constitute an Audit Committee)
Section 177 of the Companies Act, 2013 read with SS-1; Regulation 18 of the SEBI (LODR) Regulations, 2015
(Applicable to Companies required to constitute an Audit Committee)
Section 177(4) of the Companies Act, 2013; Regulation 18(2) and (3) read with Part C of Schedule II of the SEBI (LODR) Regulations, 2015
The meeting is required to have the prescribed quorum present. Members attending through video conferencing are counted for quorum. Key items typically placed before the Committee include:
(Applicable to Companies required to constitute an Audit Committee)
Section 177(8) of the Companies Act, 2013
The Committee’s recommendations, such as on the financial statements and auditors, are placed before the Board. Where the Board does not accept a recommendation of the Audit Committee, the reasons are required to be disclosed in the Board’s report.
(Applicable to Companies required to constitute an Audit Committee)
Section 118 of the Companies Act, 2013 read with Paragraph 7 of SS-1
(Applicable in case of Listed Company)
Regulations 27(2) and 46 of the SEBI (LODR) Regulations, 2015
Default | Provision | Penalty |
Contravention of Section 177 (constitution, composition, functioning) | Section 178(8) | ₹5 lakh on company and ₹1 lakh on every officer in default |
Default in minutes / Secretarial Standards | Section 118(11) | ₹25,000 on company and ₹5,000 on every officer in default, per meeting |
Non-compliance with composition of Audit Committee | Regulation 18(1), SEBI SOP Circular | ₹2,000 per day of non-compliance |
Delay in corporate governance report | Regulation 27(2), SEBI SOP Circular | ₹2,000 per day of default |
Delay in disclosures under the SEBI (LODR) Regulations | Section 15A(b), SEBI Act, 1992 | ₹1 lakh, up to ₹1 lakh per day of default (maximum ₹1 crore) |
Day 0 = Date of Audit Committee Meeting
Timeline | Action | Applies to |
Day 0 − 7 days | Notice, agenda and papers to Committee members | All applicable companies |
Day 0 | Audit Committee Meeting held | All applicable companies |
Same day or later | Recommendations placed before the Board | All applicable companies |
Day 0 + 15 days | Draft minutes circulated | All applicable companies |
Day 0 + 30 days | Minutes signed | All applicable companies |
Change + 2 working days | Committee composition updated on website | Listed Company |
Quarter-end + 21 days | Corporate governance report with Committee details | Listed Company |
Disclaimer: The information contained in this Article is intended solely for personal non-commercial use of the user who accepts full responsibility of its use. The information in the article is general in nature and should not be considered to be legal, tax, accounting, consulting or any other professional advice. We make no representation or warranty of any kind, express or implied regarding the accuracy, adequacy, reliability or completeness of any information on our page/article.