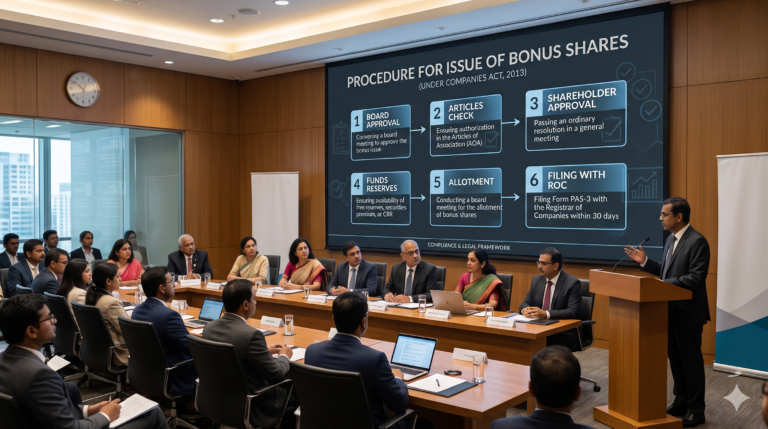
Procedure for Issue of Bonus Shares under the Companies Act, 2013

A bonus issue converts a company’s accumulated reserves into share capital by issuing fully paid-up shares to existing shareholders free of cost, in proportion to their holding. No money changes hands, but the paid-up capital rises, the reserves fall by the same amount, and the market price per share adjusts to the larger number of shares.

Because a bonus issue capitalises reserves, the law restricts the sources that may be used and the conditions the company is required to meet. Once the Board announces it, it cannot be withdrawn. This article walks through the full procedure, from the Board’s recommendation to the credit of shares and ROC filings, with the timeline for each step.

Governing law: Sections 39, 56, 63, 88, 117 and 179(3) of the Companies Act, 2013; Rule 14 of the Companies (Share Capital and Debentures) Rules, 2014; Chapter IX of the SEBI (ICDR) Regulations, 2018; Regulations 28, 29, 30, 31, 42 and 44 of the SEBI (LODR) Regulations, 2015

Applies to: All Companies having share capital (additional steps for Listed Company)

Approval required: Board recommendation and members’ approval in general meeting (ordinary resolution, unless the Articles require otherwise)

Key ROC forms: e-Form PAS-3; e-Form SH-7 (if authorised capital is increased); e-Form MGT-14 (public companies, for the allotment resolution)


Sources and Conditions for Bonus Issue

Condition

Requirement

Provision

Permitted sources

Free reserves, securities premium account, or capital redemption reserve account

Section 63(1)

Excluded source

Reserves created by revaluation of assets cannot be capitalised

Proviso to Section 63(1)

Authority

The Articles are required to authorise the issue

Section 63(2)(a)

Approval

Recommended by the Board and authorised by members in general meeting

Section 63(2)(b)

No defaults

No default in payment of interest or principal on fixed deposits or debt securities, or in statutory dues of employees such as provident fund, gratuity and bonus

Section 63(2)(c) and (d)

Partly paid shares

Any partly paid-up shares outstanding on the date of allotment are required to be made fully paid-up

Section 63(2)(e)

Not in lieu of dividend

Bonus shares cannot be issued in lieu of dividend

Section 63(3)

No withdrawal

Once announced by the Board, the bonus issue cannot be withdrawn

Rule 14

If the post-bonus paid-up capital will exceed the authorised capital, the authorised capital is required to be increased first, usually at the same general meeting. Listed companies are also required to meet the conditions in Regulations 293 and 294 of the SEBI (ICDR) Regulations, including that bonus shares are issued only out of free reserves built from genuine profits or securities premium collected in cash.

Step-by-Step Procedure
Step 1: Notice and Agenda for the Board Meeting – at least 7 days before the meeting
(Applicable to All Companies)
Section 173(3) of the Companies Act, 2013 read with SS-1
  • Notice of the Board Meeting is required to be given in writing to every director at the address registered with the company, by hand, post or electronic means.
  • The notice is required to be accompanied by the agenda, notes on agenda, draft resolutions and supporting papers for the proposed bonus issue.
  • The notes are required to set out the bonus ratio, the number of shares, the reserves to be capitalised, confirmation of the Section 63 conditions, the record date and the draft notice of the general meeting.
  • A meeting to transact urgent business may be called at shorter notice, provided at least one independent director (if any) is present. If none is present, the decisions are final only on ratification by at least one independent director.
Step 2: Prior Intimation to Stock Exchanges – at least 2 working days before the meeting
(Applicable in case of Listed Company)
Regulation 29 of the SEBI (LODR) Regulations, 2015

Prior intimation of the date of the meeting at which the Board will consider the proposal for bonus issue is required to be given to the stock exchanges. The 2 working days exclude the date of intimation and the date of the meeting.

Step 3: Closure of Trading Window – as per the company’s insider trading code
(Applicable in case of Listed Company)
Regulation 9 read with Schedule B of the SEBI (Prohibition of Insider Trading) Regulations, 2015

A proposed bonus issue is a change in capital structure and is unpublished price sensitive information. The trading window for designated persons is required to be closed until 48 hours after the information is made public. The closure is commonly intimated to the stock exchanges.

Step 4: Board Meeting to Recommend the Bonus Issue – on the date fixed
(Applicable to All Companies)
Sections 63, 173 and 174 of the Companies Act, 2013 read with SS-1
  • The Board is required to approve and recommend the bonus issue, the ratio, the amount to be capitalised and the reserves from which it will be drawn.
  • The Board is required to approve the notice of the general meeting (or postal ballot) and, where needed, the proposal to increase the authorised capital.
  • Listed companies are required to apply to the stock exchanges for in-principle approval within 5 working days of the Board Meeting.
Step 5: Disclosure of Outcome to Stock Exchanges and Website – within 30 minutes of conclusion of the meeting
(Applicable in case of Listed Company)
Regulation 30(6) and 30(8) read with Schedule III of the SEBI (LODR) Regulations, 2015
  • The outcome of the meeting, including the bonus ratio and the proposed date of the general meeting, is required to be disclosed to the stock exchanges within 30 minutes of the conclusion of the meeting, along with the time of commencement and conclusion of the meeting.
  • If the meeting ends after trading hours but more than 3 hours before the next trading session starts, the disclosure is required within 3 hours of its conclusion.
  • The same disclosure is required to be hosted on the company’s website simultaneously and retained there for at least 5 years (Regulation 30(8)).
Step 6: Minutes of the Board Meeting – draft within 15 days, signed within 30 days
(Applicable to All Companies)
Section 118 of the Companies Act, 2013 read with Paragraph 7 of SS-1
  • Draft minutes are required to be circulated to all members of the Board within 15 days of the meeting. Members may give their comments within 7 days of receipt.
  • Minutes are required to be entered in the Minutes Book within 30 days of the meeting and signed by the Chairman.
  • A copy of the signed minutes is required to be circulated to all members within 15 days of signing.
Step 7: Notice of General Meeting to Members – at least 21 clear days before the meeting
(Applicable to All Companies)
Sections 101 and 102 of the Companies Act, 2013 read with Rule 18 of the Companies (Management and Administration) Rules, 2014 and SS-2
  • Notice is required to be sent to every member, the legal representative of a deceased member, the assignee of an insolvent member, every director and the statutory auditors (and the secretarial auditor and debenture trustee, where applicable), by hand, post, courier or e-mail.
  • Notice is required to be given at least 21 clear days before the meeting, excluding the day of sending and the day of the meeting, and placed on the company’s website, if any.
  • An explanatory statement under Section 102 is required to be annexed, setting out the material facts, including the nature of concern or interest of directors, KMP and their relatives.
  • The explanatory statement is required to set out the bonus ratio, the amount to be capitalised, the reserves used and the effect on the share capital.
  • The meeting may be called at shorter notice with the consent of a majority in number of members entitled to vote who represent at least 95% of the paid-up share capital carrying voting rights.
Step 8: Submission of Notice to Stock Exchanges – within 12 hours of dispatch of notice
(Applicable in case of Listed Company)
Regulation 30 read with Para A, Part A of Schedule III of the SEBI (LODR) Regulations, 2015

The notice of the general meeting is required to be submitted to the stock exchanges and hosted on the company’s website simultaneously.

Step 9: Newspaper Advertisement of Dispatch of Notice and E-Voting – at least 21 days before the meeting
(Applicable to Listed Companies and Companies having 1,000 or more members)
Section 108 of the Companies Act, 2013 read with Rule 20(4)(v) of the Companies (Management and Administration) Rules, 2014; Regulation 30 of the SEBI (LODR) Regulations, 2015
  • An advertisement is required to be published, on completion of dispatch of notice, in one vernacular newspaper and one English newspaper circulating in the district where the registered office is situated.
  • The advertisement is required to state the completion of dispatch, the cut-off date, the e-voting period, the manner of voting and the contact details for grievances.
  • Listed companies are required to submit a copy of the advertisement to the stock exchanges and host it on their website within 24 hours of publication.
Step 10: Cut-off Date and Remote E-Voting – e-voting open for at least 3 days, closing at 5:00 p.m. on the day before the meeting
(Applicable to Listed Companies and Companies having 1,000 or more members)
Section 108 of the Companies Act, 2013 read with Rule 20 of the Companies (Management and Administration) Rules, 2014
  • The cut-off date for determining voting eligibility is required to be not earlier than 7 days before the meeting.
  • A scrutiniser is required to be appointed, after obtaining his or her consent, to scrutinise the e-voting and the voting at the meeting.
  • Remote e-voting is required to remain open for at least 3 days and to close at 5:00 p.m. on the date preceding the meeting.
Step 11: Holding the General Meeting – on the date fixed
(Applicable to All Companies)
Sections 100, 103 and 108 of the Companies Act, 2013 read with SS-2
  • The meeting is required to have the prescribed quorum present: for a public company, 5, 15 or 30 members personally present depending on whether the membership is up to 1,000, between 1,000 and 5,000, or more than 5,000; for a private company, 2 members.
  • Members are required to authorise the bonus issue by an ordinary resolution, unless the Articles require a special resolution. Any increase in authorised capital or alteration of Articles is taken up at the same meeting.
Step 12: Proceedings, Scrutiniser’s Report and Voting Results – proceedings within 12 hours; voting results within 2 working days
(Applicable in case of Listed Company)
Regulations 30 and 44(3) of the SEBI (LODR) Regulations, 2015 read with Rule 20(4) of the Companies (Management and Administration) Rules, 2014
  • A summary of the proceedings of the meeting is required to be submitted to the stock exchanges within 12 hours of its conclusion.
  • The scrutiniser is required to submit a consolidated report of the votes cast to the Chairman, who declares the result.
  • Voting results, along with the scrutiniser’s report, are required to be submitted to the stock exchanges within 2 working days of the conclusion of the meeting and hosted on the company’s website.
Step 13: Minutes of the General Meeting – within 30 days of the meeting
(Applicable to All Companies)
Section 118 of the Companies Act, 2013 read with Paragraph 17 of SS-2

Minutes are required to be entered in the Minutes Book and signed by the Chairman within 30 days of the conclusion of the meeting.

Step 14: Intimation of Record Date – at least 3 working days before the record date
(Applicable in case of Listed Company)
Regulation 42 of the SEBI (LODR) Regulations, 2015

Where a record date is fixed for determining shareholders entitled to bonus shares, prior notice is required to be given to the stock exchanges at least 3 working days in advance, excluding the date of intimation and the record date, stating the purpose of the record date. The intimation is also required to be hosted on the company’s website.

As clarified by the stock exchanges in February 2025, there is also required to be a gap of at least 3 working days between the date of Board or shareholder approval and the record date, excluding both dates.

Step 15: Allotment of Bonus Shares – Listed Company: within 2 months of the Board Meeting recommending the issue
(Applicable to All Companies)
Sections 63 and 179(3)(c) of the Companies Act, 2013; Regulation 295 of the SEBI (ICDR) Regulations, 2018
  • The Board, or a committee authorised by it, allots the bonus shares to members on the record date in the approved ratio. Fractional entitlements are dealt with as approved by members.
  • Listed companies are required to implement the bonus issue within 2 months of the Board Meeting where shareholder approval is required, and within 15 days where it is not.
  • For listed companies, the deemed date of allotment is the working day after the record date (T+1), and the bonus shares are required to be credited and available for trading on T+2, where T is the record date.
  • Notice, prior intimation, outcome disclosure and minutes of this Board Meeting follow the same timelines as Steps 1 to 6.
Step 16: Filing of Board Resolution with ROC – within 30 days of the meeting
(Applicable to Public Companies)
Section 117 read with Section 179(3) of the Companies Act, 2013

The Board resolution for allotment of bonus shares falls under Section 179(3) and is required to be filed with the Registrar of Companies in e-Form MGT-14. Private companies are exempt from filing resolutions passed under Section 179(3).

Step 17: Filing of Return of Allotment (e-Form PAS-3) – within 30 days of allotment
(Applicable to All Companies)
Section 39(4) of the Companies Act, 2013 read with Rule 12 of the Companies (Prospectus and Allotment of Securities) Rules, 2014

A return of allotment is required to be filed with the Registrar in e-Form PAS-3, with the certified copies of the Board and members’ resolutions and the list of allottees.

Step 18: Credit of Shares, Certificates and Register of Members – credit by T+2 (Listed); certificates within 2 months
(Applicable to All Companies)
Sections 56(4) and 88 of the Companies Act, 2013; Rules 9A and 9B of the Companies (Prospectus and Allotment of Securities) Rules, 2014
  • Where shares are in demat form, the corporate action is required to be completed with the RTA and depositories. Listed companies are required to submit the documents for credit by 12 noon on T+1.
  • Where physical certificates are legally permitted, share certificates are required to be issued within 2 months of allotment.
  • Stamp duty on the issue of shares is required to be paid, and the Register of Members is required to be updated with the new shareholding.
Step 19: Listing and Shareholding Pattern – within 10 days of allotment (shareholding pattern)
(Applicable in case of Listed Company)
Regulations 28 and 31 of the SEBI (LODR) Regulations, 2015
  • Listing and trading approval for the bonus shares is required to be obtained from the stock exchanges.
  • Where the capital structure changes by more than 2%, the revised shareholding pattern is required to be filed with the stock exchanges within 10 days.
Post-Meeting Filings and Disclosures

Filing / Disclosure

Authority

Due Date

Applies to

Outcome of Board Meeting (bonus recommended)

Stock Exchanges and website

Within 30 minutes of conclusion

Listed Company

In-principle approval application

Stock Exchanges

Within 5 working days of Board Meeting

Listed Company

Voting results

Stock Exchanges and website

Within 2 working days of general meeting

Listed Company

Record date intimation

Stock Exchanges and website

At least 3 working days before record date

Listed Company

e-Form SH-7 (if authorised capital increased)

Registrar of Companies

Within 30 days of general meeting

All Companies

e-Form PAS-3

Registrar of Companies

Within 30 days of allotment

All Companies

e-Form MGT-14 (allotment resolution)

Registrar of Companies

Within 30 days of allotment

Public Companies

Shareholding pattern

Stock Exchanges

Within 10 days of allotment

Listed Company

Penalties for Non-Compliance

Default

Provision

Penalty

Failure to file PAS-3

Section 39(5)

₹1,000 per day of default or ₹1 lakh, whichever is less, on company and every officer in default

Failure to issue share certificates in time

Section 56(6)

₹50,000 on company and every officer in default

Contravention of Section 63 conditions

Section 450

₹10,000 on company and every officer in default, plus ₹1,000 per day of continuing default (maximum ₹2 lakh for company, ₹50,000 for officers)

Non-filing or late filing of MGT-14

Section 117(2)

₹10,000 on company and every officer in default, plus ₹100 per day (maximum ₹2 lakh for company, ₹50,000 for officers)

Failure to give notice of Board Meeting

Section 173(4)

₹25,000 on every officer whose duty it was to give notice

Default in minutes / Secretarial Standards

Section 118(11)

₹25,000 on company and ₹5,000 on every officer in default, per meeting

Delay in prior intimation

Regulation 29, SEBI SOP Circular

₹10,000 per instance per item

Delay in implementing bonus issue

Regulation 295, SEBI (ICDR); SEBI circular of 19 August 2019

Fine for each day of delay, as specified by SEBI, in addition to other action

Delay in disclosures under the SEBI (LODR) Regulations

Section 15A(b), SEBI Act, 1992

₹1 lakh, up to ₹1 lakh per day of default (maximum ₹1 crore)


Bonus Issue at a Glance

Day 0 = Date of Board Meeting recommending the bonus issue; T = Record date

Timeline

Action

Applies to

Day 0 − 7 days

Notice, agenda and notes to directors

All Companies

Day 0 − 2 working days

Prior intimation to stock exchanges

Listed Company

Day 0

Board recommends bonus issue

All Companies

Day 0 + 30 minutes

Outcome to stock exchanges and website

Listed Company

Day 0 + 5 working days

In-principle approval application

Listed Company

General meeting − 21 clear days

Notice of general meeting dispatched

All Companies

General meeting

Members authorise bonus issue

All Companies

T − 3 working days

Record date intimation

Listed Company

T + 1

Deemed date of allotment

Listed Company

T + 2

Bonus shares credited and tradable

Listed Company

Day 0 + 2 months

Bonus issue implemented (latest)

Listed Company

Allotment + 30 days

PAS-3 and MGT-14 filed

All Companies / Public Companies


Disclaimer: The information contained in this Article is intended solely for personal non-commercial use of the user who accepts full responsibility of its use. The information in the article is general in nature and should not be considered to be legal, tax, accounting, consulting or any other professional advice. We make no representation or warranty of any kind, express or implied regarding the accuracy, adequacy, reliability or completeness of any information on our page/article. 
To stay updated Subscribe to our newsletter today

Explore other Legal updates on the Corplico and follow us on LinkedIn to stay updated 

Post Views: 11

Schedule A Demo