A related party transaction is a contract or arrangement between a company and a person who is in a position to influence it, such as a director, KMP, their relatives, or a holding, subsidiary or associate company. Because these transactions carry a risk of conflict of interest, the law requires them to be approved by people who are not interested in them.
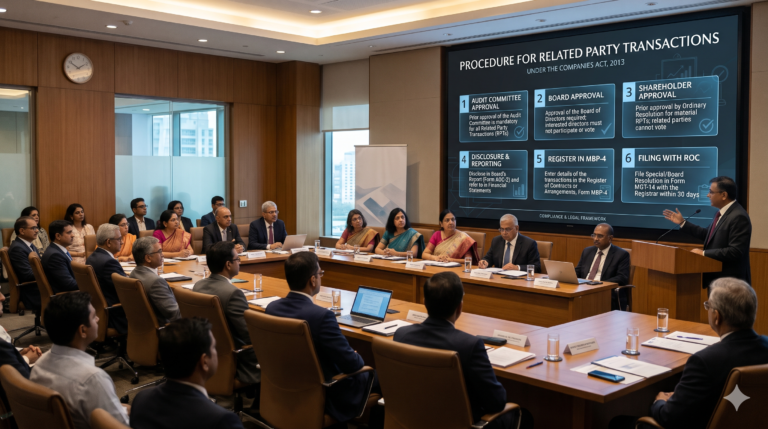
Up to three levels of approval can apply: the Audit Committee, the Board and the shareholders. This article explains when each applies and walks through the procedure, with the timeline for each step.
Governing law: Sections 2(76), 177, 184 and 188 of the Companies Act, 2013; Rule 15 of the Companies (Meetings of Board and its Powers) Rules, 2014; Regulation 23 and Schedule XII of the SEBI (LODR) Regulations, 2015 Applies to: All Companies (additional requirements for Listed Company) Covered transactions: Sale, purchase or supply of goods or materials; sale or purchase of property; leasing; availing or rendering services; appointment of agents; appointment to an office or place of profit; underwriting of securities Key record: Register of contracts in Form MBP-4; Form AOC-2 in Board’s report |
Approval | When Required | Provision |
Audit Committee | All RPTs and subsequent modifications, in companies that have an Audit Committee. Listed: all RPTs, including those of subsidiaries above specified thresholds | Section 177(4)(iv); Regulation 23(2) |
Board | RPTs covered by Section 188(1) that are not in the ordinary course of business or not at arm’s length | Section 188(1) |
Shareholders (Companies Act) | Section 188 RPTs that exceed the thresholds in Rule 15(3), such as 10% of turnover or net worth, or office of profit with monthly remuneration above ₹2.5 lakh | Section 188(1); Rule 15(3) |
Shareholders (Listed) | Material RPTs, determined by the scale-based thresholds in Schedule XII (effective 18 December 2025), and their material modifications, whether or not in the ordinary course | Regulation 23(4) |
For listed companies, Schedule XII sets the following materiality thresholds:
Consolidated Turnover of Listed Entity | RPT is Material if it Exceeds |
Up to ₹20,000 crore | 10% of annual consolidated turnover |
Above ₹20,000 crore and up to ₹40,000 crore | ₹2,000 crore plus 5% of turnover above ₹20,000 crore |
Above ₹40,000 crore | ₹3,000 crore plus 2.5% of turnover above ₹40,000 crore, subject to a maximum of ₹5,000 crore |
Turnover is taken from the audited consolidated financial statements of the preceding financial year. The listed entity’s policy on materiality of RPTs is required to be updated for these thresholds.
The notice of the general meeting is required to be submitted to the stock exchanges and hosted on the company’s website simultaneously.
A listed company is required to file disclosures of RPTs with the stock exchanges in the format specified by SEBI, on a consolidated basis, every six months, and publish them on its website.
Transactions entered into without approval. A contract entered into without the required Board or shareholder approval may be ratified within 3 months; otherwise it is voidable at the option of the Board or shareholders, and the director concerned is required to indemnify the company for any loss (Section 188(3)).
Default | Provision | Penalty |
Director or employee entering into an RPT in violation of Section 188 | Section 188(5) | ₹25 lakh in a listed company; ₹5 lakh in any other company |
Contravention of Section 177 (Audit Committee) | Section 178(8) | ₹5 lakh on company and ₹1 lakh on every officer in default |
Failure by director to disclose interest | Section 184(4) | ₹1 lakh on the director |
Non-disclosure in Board’s report | Section 134(8) | ₹3 lakh on company and ₹50,000 on every officer in default |
Delay in half-yearly RPT disclosure | Regulation 23(9), SEBI SOP Circular | ₹5,000 per day of default |
Delay in disclosures under the SEBI (LODR) Regulations | Section 15A(b), SEBI Act, 1992 | ₹1 lakh, up to ₹1 lakh per day of default (maximum ₹1 crore) |
Day 0 = Date of entering into the transaction
Timeline | Action | Applies to |
Before Day 0 | Classification and threshold testing | All Companies |
Before Day 0 | Audit Committee approval | Companies with Audit Committee |
Before Day 0 | Board approval at a meeting | Section 188 transactions |
Before Day 0 | Shareholder approval | Above Rule 15(3) / Schedule XII thresholds |
Day 0 | Entry in Register MBP-4 | All Companies |
Results + 15 days | Half-yearly RPT disclosure | Listed Company |
Annually | Form AOC-2 in Board’s report | All Companies |
Disclaimer: The information contained in this Article is intended solely for personal non-commercial use of the user who accepts full responsibility of its use. The information in the article is general in nature and should not be considered to be legal, tax, accounting, consulting or any other professional advice. We make no representation or warranty of any kind, express or implied regarding the accuracy, adequacy, reliability or completeness of any information on our page/article.