When a company repays a secured loan in full, the charge it created on its assets in favour of the lender has to be removed from the Registrar’s records. Until that is done, the MCA records continue to show the assets as encumbered, which can hold up fresh borrowing, sale of assets and due diligence.
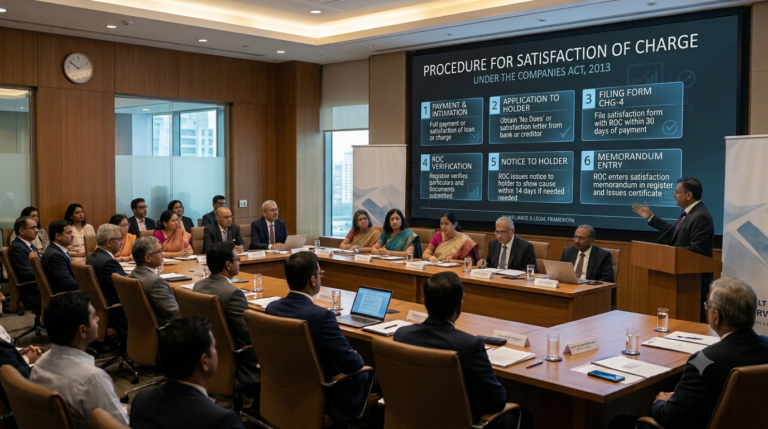
This article walks through the procedure for reporting satisfaction of a charge, from obtaining the lender’s no-objection to filing e-Form CHG-4, with the timeline for each step.
Governing law: Sections 82, 83, 85, 86 and 87 of the Companies Act, 2013; Rule 8 of the Companies (Registration of Charges) Rules, 2014; Regulations 30, 51 and 56 of the SEBI (LODR) Regulations, 2015 Applies to: All Companies Time limit: 30 days from payment or satisfaction; up to 300 days on application with additional fee Key ROC form: e-Form CHG-4; Register of Charges in Form CHG-7 |
As good practice, the Board takes note of the satisfaction and authorises a director or the Company Secretary to sign and file CHG-4. A resolution by circulation may be used if a meeting cannot be held in time. Listed companies disclose the outcome to the stock exchanges where it is material.
The company’s register of charges in Form CHG-7 is required to be updated to record the satisfaction. Instruments of the charge are required to be preserved for 8 years from the date of satisfaction.
Where the charge secured listed non-convertible securities, the satisfaction or release is required to be disclosed to the stock exchanges and intimated to the debenture trustee.
Where satisfaction has not been intimated within 300 days, the company may apply to the Central Government (through the Regional Director) to extend the time, on showing that the omission was accidental or due to sufficient cause and does not prejudice creditors or shareholders. The order is filed with the Registrar in e-Form INC-28.
Default | Provision | Penalty |
Contravention of Chapter VI (charges) | Section 86(1) | ₹5 lakh on the company; ₹50,000 on every officer in default |
Wilfully furnishing false information about a charge | Section 86(2) | Liable to action under Section 447 (fraud) |
Day 0 = Date of payment or satisfaction of the charge in full
Timeline | Action | Applies to |
Day 0 | Repayment; no-objection certificate obtained | All Companies |
Before Day 0 + 30 days | Board authorises filing | All Companies |
Day 0 + 30 days | CHG-4 filed; Register CHG-7 updated | All Companies |
Day 0 + 300 days | Last date for CHG-4 with additional fee | All Companies |
After Day 0 + 300 days | Condonation application to Central Government | Where applicable |
Disclaimer: The information contained in this Article is intended solely for personal non-commercial use of the user who accepts full responsibility of its use. The information in the article is general in nature and should not be considered to be legal, tax, accounting, consulting or any other professional advice. We make no representation or warranty of any kind, express or implied regarding the accuracy, adequacy, reliability or completeness of any information on our page/article.