Shares are movable property and can be transferred in the manner provided by a company’s Articles of Association. A transfer is complete in the company’s books only when the company registers it and enters the transferee’s name in the register of members, so the company’s role in checking and approving the transfer matters as much as the agreement between buyer and seller.
This article covers the transfer of shares and other securities held in physical form under Section 56, the restrictions that now require securities of many companies to be dematerialised first, and the timeline for each step.
Governing law: Sections 44, 56, 58 and 88 of the Companies Act, 2013; Rule 11 of the Companies (Share Capital and Debentures) Rules, 2014; Rules 9A and 9B of the Companies (Prospectus and Allotment of Securities) Rules, 2014; Regulations 20 and 40 of the SEBI (LODR) Regulations, 2015; Indian Stamp Act, 1899 Applies to: All Companies (additional restrictions for Listed Company and companies required to dematerialise) Approved by: Board of Directors, or a committee such as the Stakeholders Relationship Committee Key form: Form SH-4 (instrument of transfer) |
Company | Transfer Route | Provision |
Listed Company | Transfer only in demat form; physical transfer requests are not processed | Regulation 40(1), SEBI (LODR) |
Unlisted public company | Securities are required to be dematerialised before transfer | Rule 9A(4) |
Private company other than a small company | Securities are required to be dematerialised before transfer (Rule 9B deadline: 30 June 2025) | Rule 9B |
Small company, and other private companies not yet covered | Physical transfer through Form SH-4 permitted | Section 56; Rule 11 |
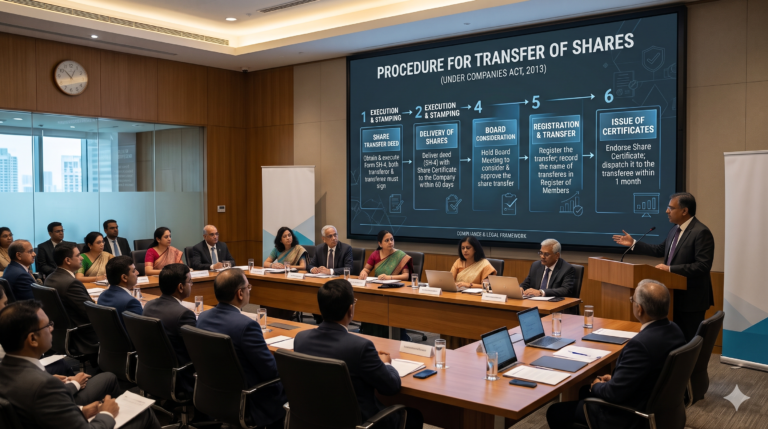
Where securities are held in demat form, the transfer happens through the depository system and the depository’s records are evidence of ownership. The steps below apply where a physical transfer is still permitted.
The duly stamped instrument, together with the share certificate (or the letter of allotment, where no certificate has been issued), is required to be delivered to the company by the transferor or the transferee within 60 days of execution. Where the instrument is lost or delivered late, the company may still register the transfer on such terms as to indemnity as the Board thinks fit.
Where the company refuses to register the transfer, notice of refusal with reasons is required to be sent to the transferor and transferee within 30 days of delivery of the instrument. The transferee may appeal to the Tribunal within 30 days of receiving the notice (60 days for a public company), or within 60 days of delivery where no notice is sent (90 days for a public company).
The endorsed or new certificates are required to be delivered within one month of the date on which the company received the instrument of transfer.
Where equity instruments are transferred between a person resident in India and a person resident outside India, Form FC-TRS is required to be filed on the RBI’s FIRMS portal by the resident party within 60 days of receipt or remittance of the consideration. Pricing guidelines under FEMA also apply.
Listed companies. A transferor’s objection to a transfer is required to be notified to the transferee, and if the transferor does not obtain a court order within 60 working days of objecting, the company proceeds with the transfer (Regulation 40(5)). Transfers are not registered where there is a statutory prohibition or an attachment or prohibitory order (Regulation 40(4)).
Default | Provision | Penalty |
Failure to deliver certificates within one month | Section 56(6) | ₹50,000 on company and every officer in default |
Failure to maintain Register of Members | Section 88(5) | ₹3 lakh on company and ₹50,000 on every officer in default |
Registration of transfer in breach of demat requirements | Section 450 | ₹10,000 on company and every officer in default, plus ₹1,000 per day of continuing default (maximum ₹2 lakh for company, ₹50,000 for officers) |
Failure to give notice of Board Meeting | Section 173(4) | ₹25,000 on every officer whose duty it was to give notice |
Default in minutes / Secretarial Standards | Section 118(11) | ₹25,000 on company and ₹5,000 on every officer in default, per meeting |
Late filing of FC-TRS | FEMA, 1999 | Late submission fee or compounding by the RBI |
Day 0 = Date of receipt of instrument of transfer by the company
Timeline | Action | Applies to |
Execution | SH-4 executed and stamped | All Companies |
Execution + 60 days | Instrument and certificate delivered to company | All Companies |
Day 0 + 2 weeks | Objection period for partly paid shares | Where applicable |
Next meeting | Board or committee approves transfer | All Companies |
Day 0 + 30 days | Notice of refusal (if refused) | All Companies |
Day 0 + 1 month | Certificates delivered to transferee | All Companies |
Consideration + 60 days | FC-TRS filed | Resident / non-resident transfers |
Disclaimer: The information contained in this Article is intended solely for personal non-commercial use of the user who accepts full responsibility of its use. The information in the article is general in nature and should not be considered to be legal, tax, accounting, consulting or any other professional advice. We make no representation or warranty of any kind, express or implied regarding the accuracy, adequacy, reliability or completeness of any information on our page/article.